 800-503-2102
 Chat with ZAF

Key Takeaways:
- After a minor crash, document the scene with photos, driver information, witness details, and a short written account of what happened.
- No visible vehicle damage doesn’t mean you’re injury-free, since symptoms like whiplash, headaches, or dizziness can appear later.
- You may still need to report the accident to the police or your insurer, and doing so promptly can help prevent coverage disputes later.
If you were in a minor car accident and both cars look fine, don’t assume the situation is over. You should still exchange information, take photos, and watch for delayed symptoms, because a crash with no visible damage can still lead to injury claims or insurance disputes.
Knowing what to do after a minor car accident with no damage can mean the difference between a clean resolution and a dispute you weren’t prepared for. ZAF Legal’s free AI case assessment can help you understand where you stand before you decide it’s over.
What to Do First After a Minor Car Accident With No Damage
Even when both cars look perfectly fine, your strongest protection is a record you made before anyone’s account had a chance to shift. Damage that looked like nothing at a roadside glance can surface under a mechanic’s inspection.
A driver who seemed agreeable can file a claim the next morning, and if there’s no record of what actually happened, their version of events is as valid as yours. Knowing what to collect at the scene takes minutes. Not gathering it can cost you much more.
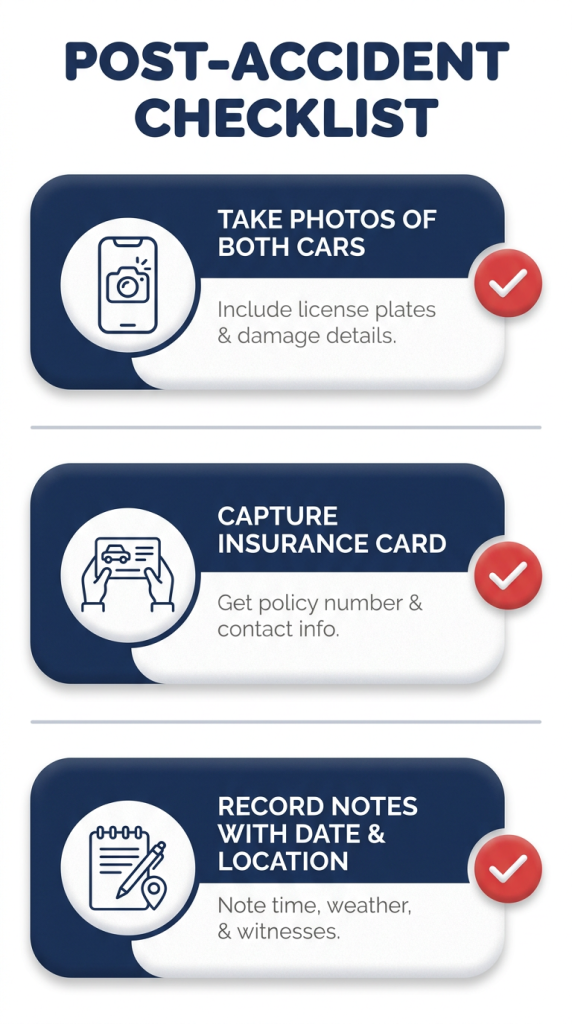
- Photograph both vehicles from multiple angles, capturing license plates, the point of contact, and the surrounding area. Include something that shows the time and location, like a timestamp on the photo or a landmark in the background.
- Write down what happened as soon as you can, while the details are fresh. A few sentences in your phone’s notes app describing how the crash occurred are far more reliable than memory alone if the facts are disputed weeks later.
- Exchange names, phone numbers, and insurance information with the other driver. Skip the roadside debate about who was at fault; that conversation rarely helps and sometimes hurts.
- Note any witnesses and, if possible, get their contact information. A neutral third party who saw the collision can be surprisingly valuable if the other driver later changes their account.
- Keep records of anything you spend or lose because of the crash, including time away from work, transportation costs, or any medical visits that follow. These details matter if a claim becomes necessary.
The goal is to give yourself options. If symptoms appear in the days ahead or the other driver files a claim you weren’t expecting, having this information already in hand puts you in a much stronger position.
What If the Other Driver Says There’s No Damage and Wants to Leave?
This is one of the most common roadside moments after a low-impact crash—and one of the riskiest to handle on good faith alone. Even if the other driver seems completely fine with moving on, you should still:
- Exchange insurance and contact information before anyone leaves
- Take photos of both vehicles from multiple angles
- Do not admit fault, even casually
- Do not rely on a verbal agreement; nothing said at the scene is enforceable later
- If anything feels off or if you notice any discomfort, report the crash
A driver who seems agreeable at the scene can change their story later, file a claim, or dispute that the crash happened at all. Informal agreements offer no protection. A few photos and an exchanged name are a small investment against a much larger headache. See our post-accident checklist for a quick reference on what to collect before you part ways.
Can You Be Hurt in a Minor Car Accident With No Damage?
Delayed injury symptoms after a car accident are more common than most people expect. The body’s adrenaline response often masks pain in the hours after a crash, so feeling fine at the scene is not always the full picture. If something feels different in the days that follow, that change deserves attention.
“I Feel Fine” Isn’t the End of the Story
The amount of vehicle damage does not predict whether someone develops chronic pain after a crash, which means a fender-bender with no visible dents can still produce real, lasting injury. Whiplash and related symptoms frequently have a delayed onset: neck pain, headaches, back pain, numbness, and dizziness can appear hours or even days after the collision. Feeling fine at the scene is not the end of the story.
What Seeing a Doctor Actually Does for You
Getting evaluated creates the medical record that insurers look for when connecting symptoms to a crash. Cost concerns are valid, and they’re worth naming directly. Care is often covered first by PIP or MedPay, where available, and then by health insurance. Some providers will also treat you under a lien, collecting from your eventual settlement rather than your wallet.
Timing Can Quietly Work Against You
Concussion and traumatic brain injury symptoms frequently appear hours after impact and can be missed without prompt evaluation. The longer symptoms go unmentioned and undocumented, the more room an insurer has to argue they are unrelated to the crash. Sorting out how long after a car accident you should see a doctor is far easier to do early than to argue about once an insurer is already questioning the connection.
Mistakes to Avoid After a Minor Car Accident With No Damage
These are the decisions that seem harmless at the scene and become harder to fix later:
- Leaving without exchanging information
- Assuming no damage means no injury
- Skipping photos
- Waiting too long to report to the police or your insurer
- Agreeing not to involve insurance without any written record
- Ignoring pain that starts a day or two later
If you’re unsure when a lawyer may help with a minor car accident, the answer is usually sooner than most people expect.
Minor Car Accident With No Damage FAQs
Even a minor crash can raise questions about reporting, insurance, and what to do if the situation changes later. Here are a few common questions drivers have after an accident with no visible damage.
Do I still need to report a minor car accident with no visible damage?
It depends on where you live. Most states require you to report a crash once damage crosses a certain dollar threshold, and some thresholds are lower than you might expect. When in doubt, a quick report costs you little. Skipping one can cost you more. In New York, for example, the reporting threshold is $1,000; any crash with damage exceeding that amount must be reported.
When does reporting a low-impact crash protect me from bigger insurance problems later?
Most insurance policies require you to notify your insurer promptly after any car accident, regardless of damage. If the other driver later files a claim, having an official record protects your version of events—and knowing whether you should give a recorded statement to your own insurer can also affect how that claim is handled. Waiting too long can give insurers grounds to deny coverage entirely.
What if neither of us wants to involve insurance?
That is your choice to make, but go in with clear eyes. If symptoms appear days later, or if the other driver files a claim first, you will wish you had a record. Collecting evidence and exchanging information does not obligate you to file a claim. It just keeps your options open.
Get Clarity Before You Decide It Is Over
Not sure whether this minor crash is really “minor”? A crash that looks clean at the scene can still turn complicated, faster than you’d expect, and in directions you can’t predict. The paper trail costs nothing to create at the scene. Not having one when the other driver’s insurer comes calling, or symptoms surface a week later, is a gap you can’t go back and close.
- Start with ZAF’s free AI assistant to check whether your situation raises injury, insurance, or claim issues before you decide to let it go
- Schedule a consultation if you want an attorney’s take on your specific situation, or call 800-503-2102
- Review our guide on steps to take after a car accident that was not your fault for a simple walkthrough of what to do next
Prefer to handle it yourself? ZAF’s DIY bundle gives you a demand draft, attorney review, and a clearer sense of what your claim is actually worth, starting around $49.99 and fully refunded if you later move to full-service representation.
This content is for informational purposes only and does not constitute legal advice, and reading the content does not create an attorney-client relationship.
.